






Quantitative Analyst @ UBS · Open-source derivatives & risk modelling · Founder, Desk2Quant
I build, test and explain numerical models for derivatives pricing, stochastic simulation, interest rates and counterparty risk — primarily in Python, C++ and R.
LinkedIn · Desk2Quant · stochPathSim · Documentation · Email
17 merged code contributions to established quantitative-finance libraries, plus 2 accepted listings in the curated awesome-quant collection.
| Project | Merged PRs | Representative engineering work |
|---|---|---|
| QuantLib · C++ | 7 | Multiple-reset swap schedule and helper pillar · Callable-bond effective duration/convexity · Overnight-future holiday accrual |
| FinancePy · Python | 10 | Hagan–West monotone-convex interpolation · Normal-vol SABR smile calibration · Scrambled Sobol QMC for Asian options |
| awesome-quant · curated resources | 2 | stochPathSim accepted · CustomDerivative accepted |
See all upstream pull requests · Open QuantLib contributions · Open FinancePy contributions
Counts checked 19 October 2026; linked GitHub searches provide the current status.
1. stochPathSim — stochastic simulation through model validation


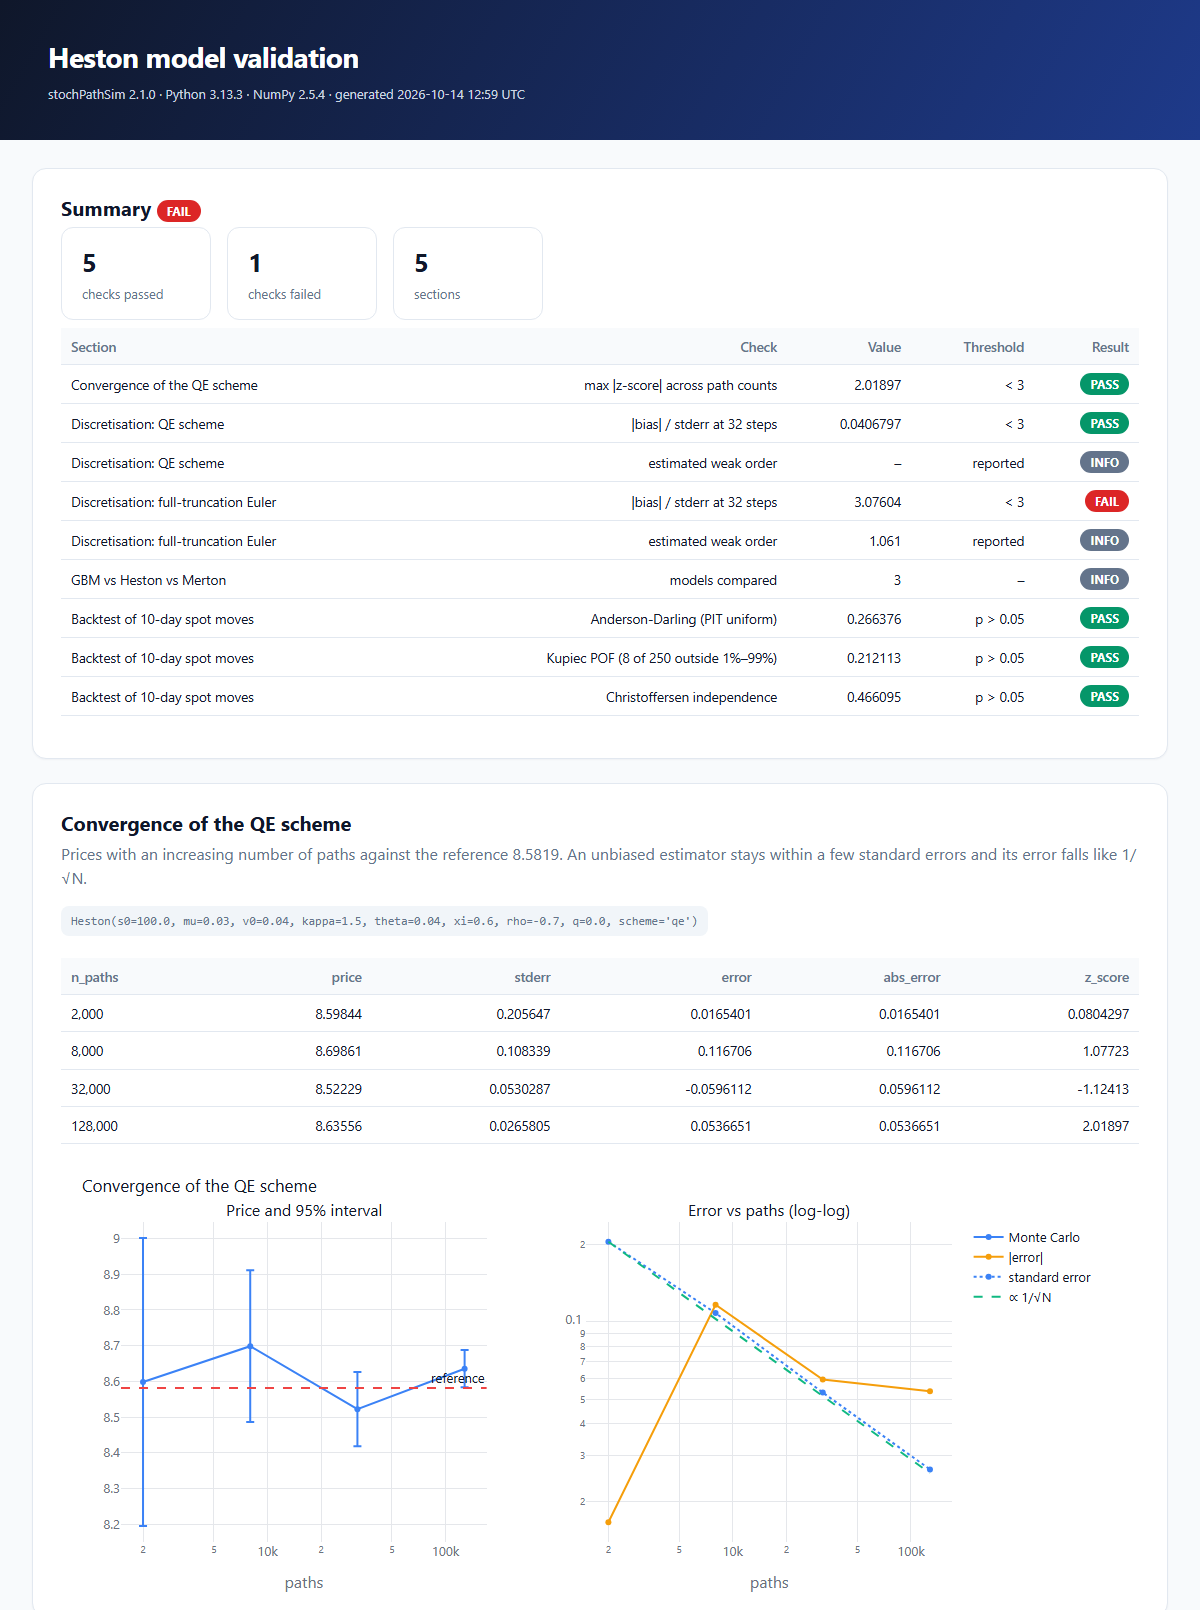
A Python package covering stochastic processes, Monte Carlo derivatives pricing, exposure/CVA, risk-factor backtesting and interactive Plotly model-validation reports.
- Models: Heston, rough Bergomi, SABR, Merton/Kou jumps, CIR, Hull–White and G2++ (among others).
- Risk: EE, PFE, effective EPE, CVA, VaR/ES, PIT and coverage/independence tests.
- Validation: reproducible examples, convergence and discretisation studies, and comparisons to analytical formulas and QuantLib.
pip install stochPathSimSource · Documentation · Examples · Tests
2. CustomDerivative — derivative pricing in R


A published CRAN package for Black–Scholes–Merton pricing, custom terminal payoffs, Monte Carlo with variance reduction, Asian/barrier examples and finite-difference Greeks.
install.packages("CustomDerivative")Source & examples · CRAN release
3. Quantitative Derivative Models — reproducible educational notebooks

A collection of pricing and risk notebooks: finite-difference methods, binomial/trinomial trees, stochastic-process examples and credit models. Educational examples, not a calibrated production pricing engine.
A reproducible teaching lab illustrating pathwise exposure, simplified CVA/DVA/funding adjustments, collateral/MPOR, a small Deep-BSDE experiment and static option-surface checks. Not independently validated or suitable for trading or regulatory use. Methods and limitations.
- UBS: quantitative risk work spanning counterparty exposures, model risk, and risk-factor backtesting.
- Previously, Reserve Bank of India: market-microstructure research.
- Desk2Quant: I develop quant-finance learning resources, interactive labs and mentoring experiences. Explore the platform.
- Education: M.Sc., IIT Jodhpur; B.Sc. (Hons.) Physics, Jamia Millia Islamia.
Research and preprints: Stochastic thermodynamics of price impact · Sinusoidal Hull–White model · Digitization and Indian bank assets
Methods: Monte Carlo · stochastic calculus · numerical PDEs · interest-rate models · XVA/CCR · model validation · backtesting
Tools: Python · C++ · R · NumPy/SciPy · PyTorch · QuantLib · Plotly · GitHub Actions · LaTeX
Also building: Desk2Quant (quant education platform) and CraftCode CLI (developer tooling).
I welcome narrowly scoped issues and pull requests on reproducible pricing models, test coverage, documentation and model-validation examples. For a proposed numerical change, please include model assumptions, a minimal reproducer, and an independent reference or regression test.